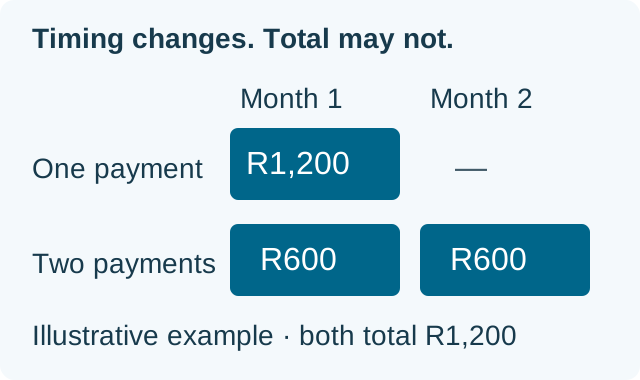
Two loans with the same headline amount can cost different amounts to repay. The useful comparison is the cash you actually receive, every fee and interest charge, the payment dates and the total payable. A lower monthly instalment can feel easier while extending repayments; a shorter term can make a single payment harder to meet.
Start with a real quotation
Write down the amount requested and the amount that will reach your bank account. Then list the interest, initiation fee, service fee and any other charge shown. Add all scheduled payments to find the total amount payable. The National Credit Regulator's consumer guide says the pre-agreement quotation should disclose the amount borrowed, instalments, interest, additional charges and payment dates before you sign.
Published example: the full repayment amount
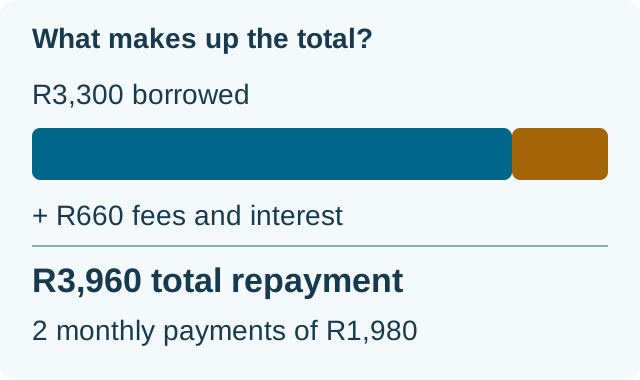
- Borrowed
- R3,300
- Fees and interest
- R660
- Total repayment
- R3,960
Compare like for like
Use the same amount needed and a repayment schedule you could realistically meet. If one product pays out less after a fee, compare the net cash received as well as the total returned. Note the due date of each payment. A loan that appears cheaper overall may be unsuitable if its next payment falls before your income arrives.
Use provider calculators carefully
FASTA says its sliders display the costs for a selected amount and number of instalments, including fees and interest. Jabulani Money says its calculator is a reference and an offer follows an affordability assessment. Treat any calculator as a starting point and verify the final quote.
Before accepting
Check the legal provider, save the quotation and agreement, and confirm the repayment method. If a payment would leave too little for essential expenses or existing debt, consider a smaller amount or an alternative to borrowing. See the personal-loan comparison for the providers currently listed on Finpanda.
A smaller instalment does not always mean a cheaper loan
A South African loan quotation has dates as well as prices
For credit agreements covered by the National Credit Act, the NCR consumer booklet describes a pre-agreement statement and quotation that sets out the proposed terms and costs, with a quotation valid for five business days. Ask for the issue date and validity period on the actual document. A calculator screenshot or a limited-time advert is not the same as your personalised quotation; approval and the final agreement still need to be confirmed.
The NCR's small-credit quotation form separates the credit advanced, initiation fee, monthly service fee, required insurance and optional items. Check which charges are already included in the instalments and which are separate. When comparing Jabulani Money, CreditBar, LendPlus or PrimeLoans, use the amount you would actually receive and keep each repayment date. Do not count an included charge twice or treat an unanswered insurance-cost question as a zero charge.
Commercial links
Jabulani Money: alternative provider
Jabulani Money is our first commercial placement. This is not a ranking by cost, service or approval chance. Finpanda may earn a commission.
Jabulani Money
- Amount
- Individual quotation
- Repayment
- Individual quotation
- Total cost
- Check your written quote
Jabulani Money supplies a loan offer after affordability assessment. Check the amount, fees and payment dates in that offer.
Paid link opens www.jabulanimoney.co.za. The provider assesses your application; approval is not guaranteed. Provider profile.
CreditBar
- Amount
- R500–R5,000
- Repayment
- 7–61 days in FAQ; another section gives 7–45. Confirm the quote.
- Total cost
- Check your written quote
CreditBar publishes a day-based range. Compare the full repayment amount and the exact due date.
Paid link opens creditbar.co.za. The provider assesses your application; approval is not guaranteed. Provider profile.
Published by Finpanda. This is a source-based guide, not a customer review or an independent lender audit. Finpanda may earn a commission from commercial links.