Mobile-home loans: land, title and financing comparisons
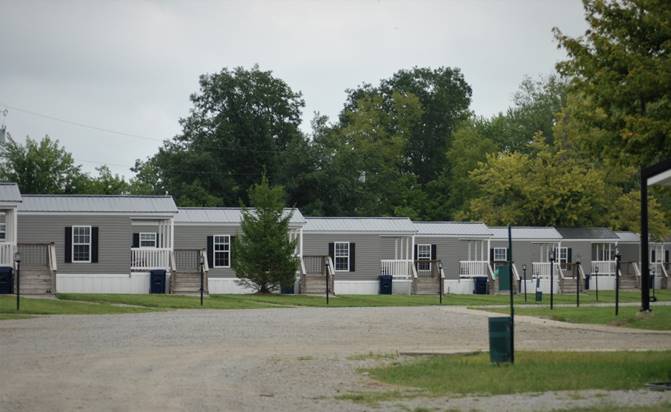
Short answer: Mobile-home or manufactured-home financing depends on the property, how the home is titled, and whether land is included. A mortgage and a personal-property or chattel loan can have different costs and protections. Ask which structure applies to the exact home before comparing payments.
Are you financing the home, the land or both?
Start with the address, the home’s details, ownership of the land and the legal classification of the property. The CFPB’s manufactured-housing research explains why land ownership and title classification affect financing. An advertisement for a monthly home payment may leave out site rent or other housing expenses. Ask for a written breakdown of what is being purchased and what secures the loan.
| Check | Mortgage route | Personal-property route |
|---|---|---|
| Collateral | Ask whether home and land are included | Ask exactly which property secures the loan |
| Property requirements | Confirm title, foundation and eligibility | Confirm home age, type and location rules |
| Cost document | Ask which mortgage disclosures apply | Request all loan fees and payment terms in writing |
| Housing budget | Include taxes, insurance and maintenance | Also include site rent and site-agreement conditions when relevant |
What costs sit outside the loan payment?
Build a budget for site rent if applicable, insurance, taxes, transport, installation, utility connection and maintenance. Ask the seller which costs are included in the quoted price. If land is leased, review the lease term and how rent can change; a payment you can afford today may not describe the full future housing budget.
How do you compare dealer financing with another offer?
Ask the seller for the home price independently of the finance payment. Then request the amount financed, term, fees, payment schedule and total repayment. Where possible, seek another quote for the same home and land arrangement. Do not compare a home-only offer with a home-and-land offer as though the difference were simply a lender discount.
A housing-budget example
Illustration only: a $650 loan payment plus $450 site rent and $150 reserved for insurance, taxes and maintenance is a $1,250 monthly budget. A competing home-and-land option with a $1,050 loan payment might still have additional costs. Compare complete budgets before deciding that the smaller loan payment is the cheaper home. These figures are invented teaching amounts, not regional prices or available loans.
Questions borrowers ask
Does owning land automatically guarantee a mortgage?
No. Title, property eligibility and underwriting still matter. Ask the lender about the specific home and land.
Is a chattel loan the same as a personal loan?
No. A personal-property loan secured by the home differs from an unsecured personal loan. Read the collateral and repossession terms.
Can I use a general personal-loan link to finance this home?
Do not assume so. This guide does not list a verified manufactured-home application; confirm the exact product and allowed use of funds.
Related US guides
- Conventional-mortgage comparisons
- Construction and installation financing questions
- Existing home-equity borrowing
- Selecting the correct lender product
Sources and editorial note
Finpanda editorial guide, revised September 28, 2026. Examples are hypothetical, not lender quotes. Check the current provider agreement and official program information for your situation. Finpanda does not approve loans.
Debt consolidation loan vs. balance transfer: compare the real cost
Short answer: A debt consolidation loan replaces debts with a loan repayment schedule. A balance transfer moves eligible debt to a credit card, potentially at a temporary promotion...
Read more
Can you pay off a personal loan early? Costs and a payoff example
Short answer: You can often pay off a personal loan early, but check the agreement for prepayment charges and request a dated payoff quote. On an interest-bearing balance, shorteni...
Read more